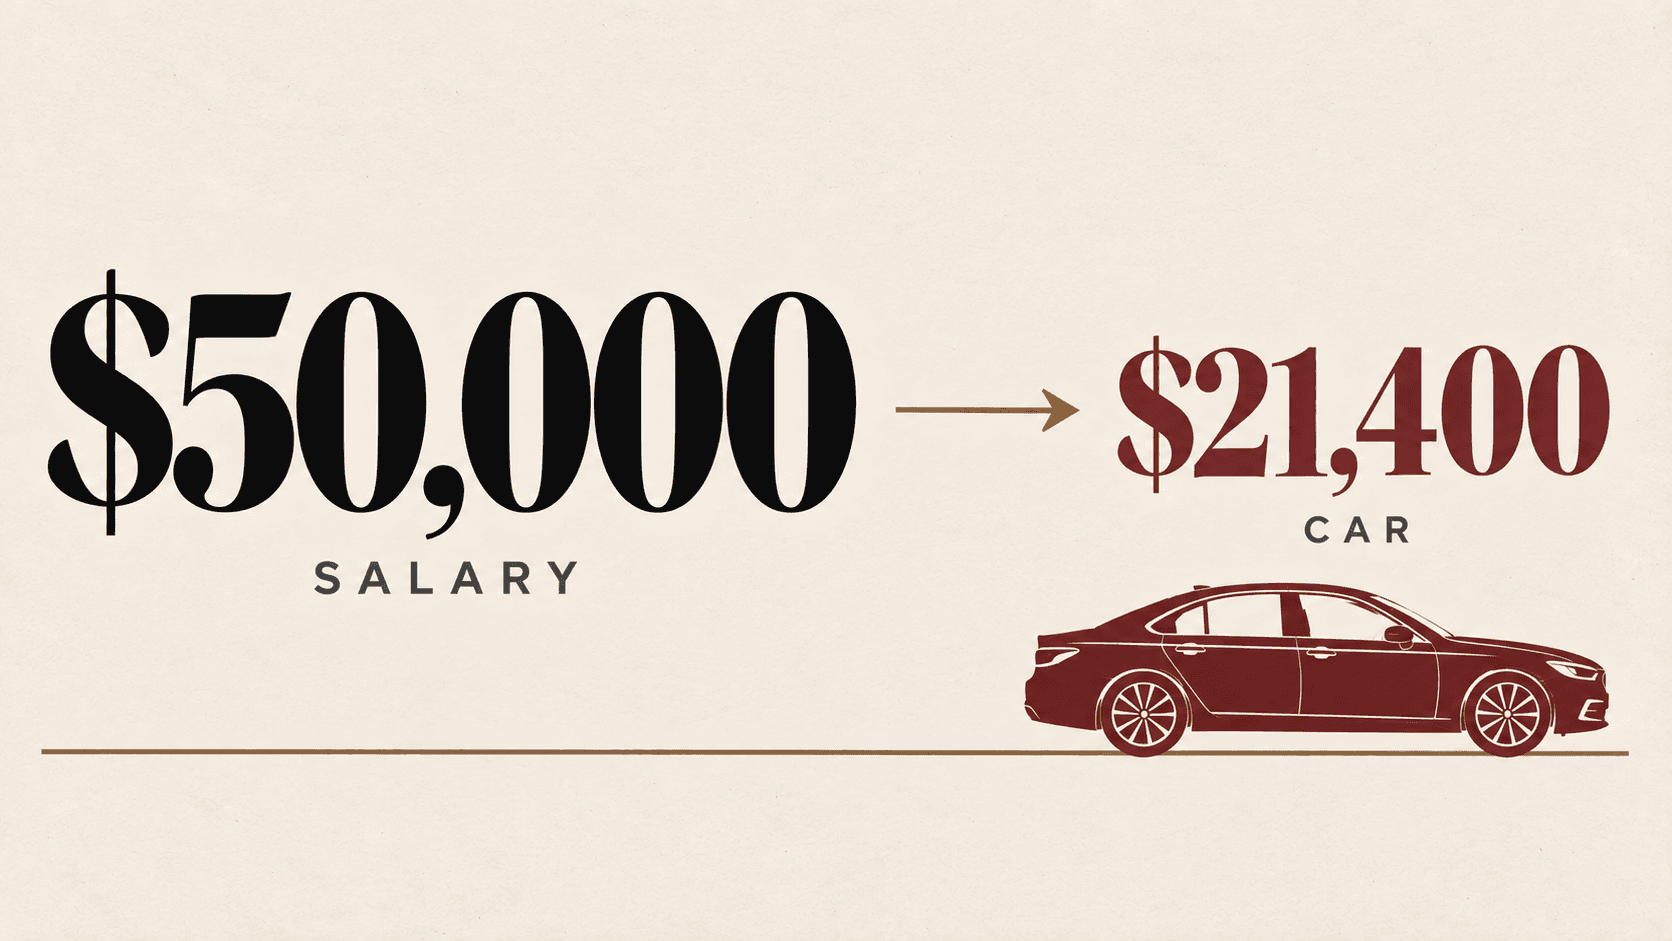Plain-English guides to the money decisions Americans actually face: credit scores, car loans, mortgages, savings, retirement and debt. The math is shown, and time-sensitive figures are dated.
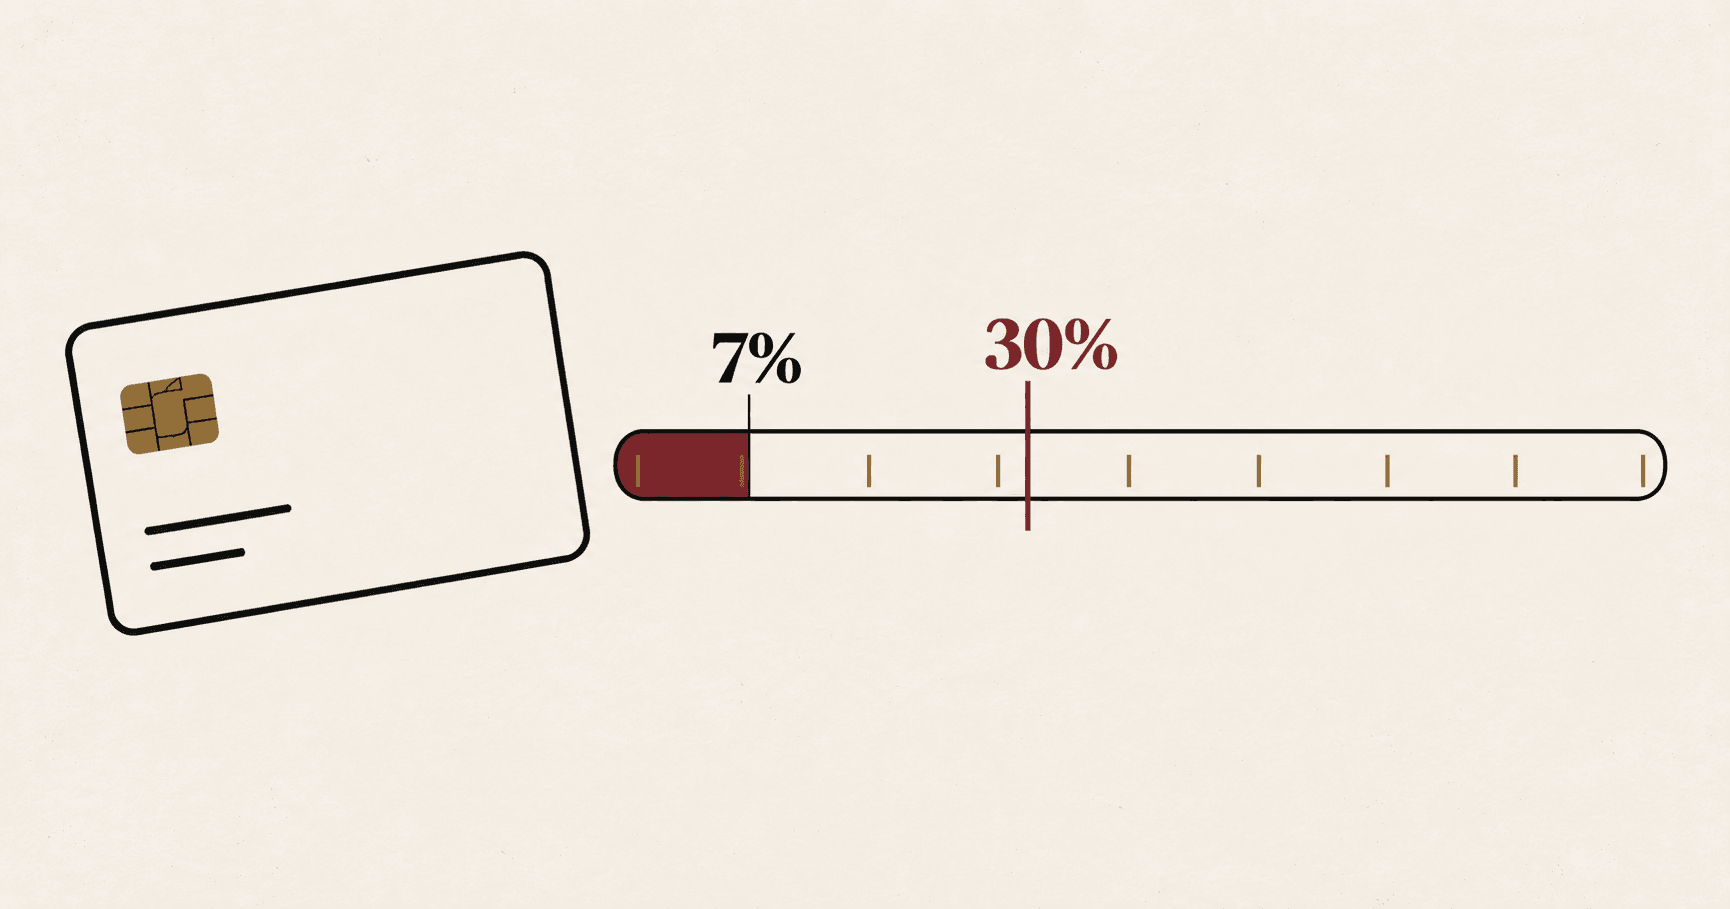
The usual advice is to keep credit card balances under 30% of your limits, but people with 800-plus scores average just 7%. Here's how credit utilization is calculated per card and overall, what to use on any limit, and how to lower the balance your issuer reports.
Paying off a credit card usually raises your credit score, but not always right away, and not always by as much as you hope. Here's how much it can move, how long it takes, which balance to pay, and the mistakes that make a score drop after a payoff.
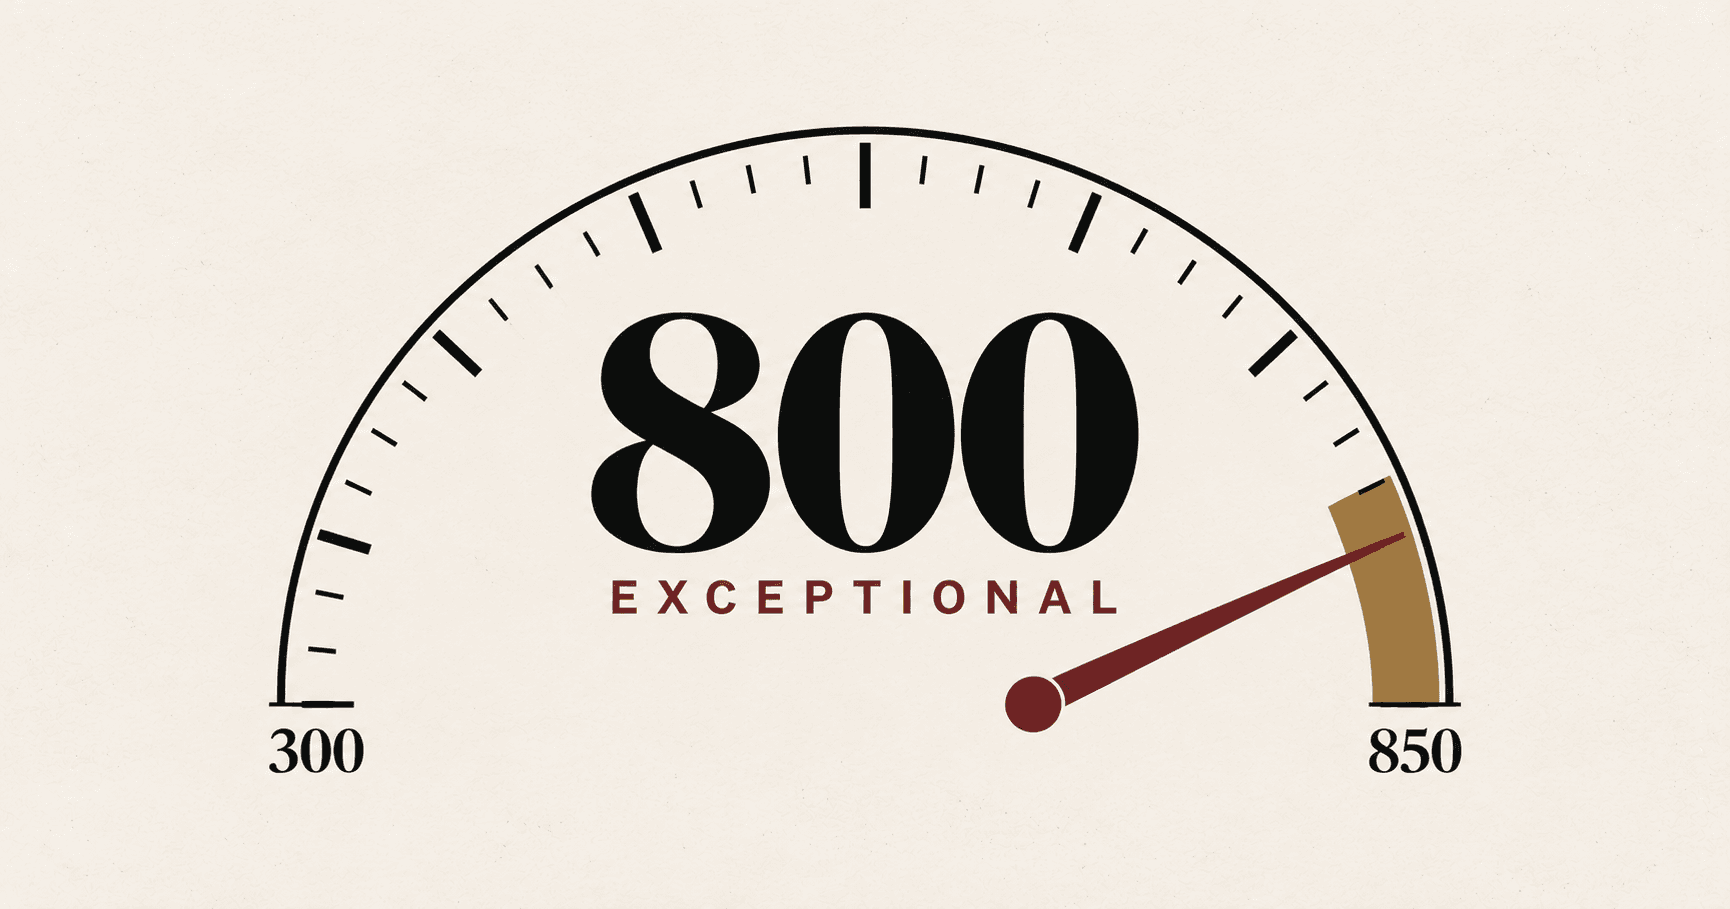
An 800 credit score is exceptional, and nearly one in four Americans has one. Here's what it actually gets you on car loans, personal loans and mortgages, why the best rates often start near 780, and the habits that get you to 800 and keep you there.
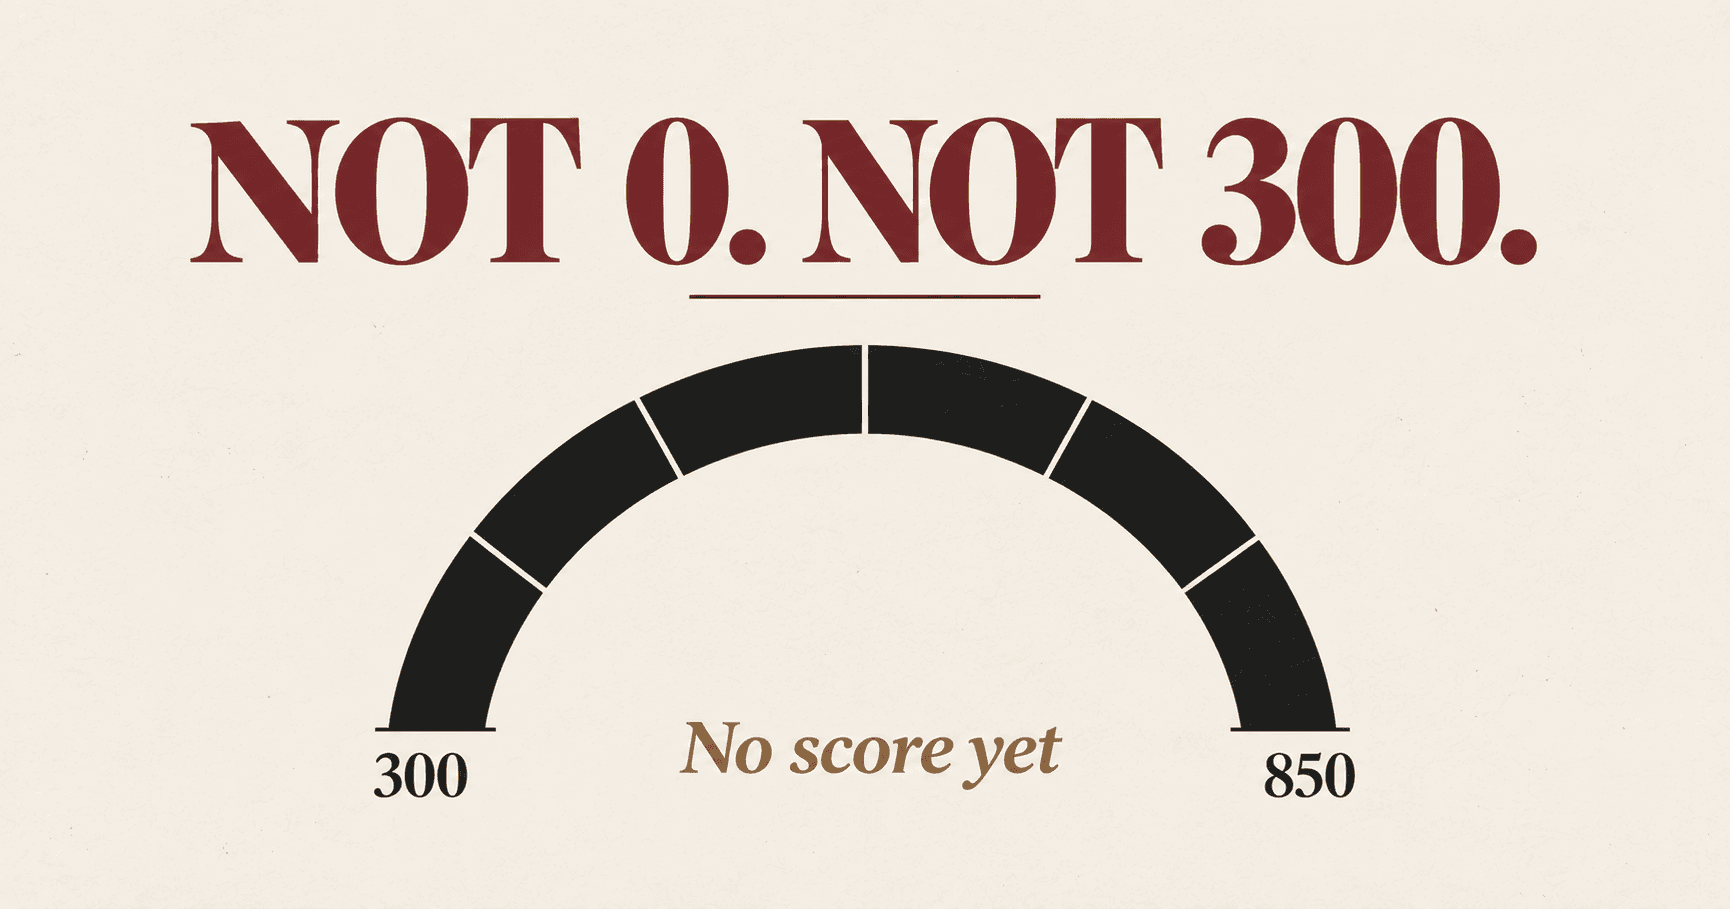
Your credit score doesn't start at zero - or at 300. With no credit history you have no score at all, and about one in ten US adults has a credit file that still can't be scored. Here's when your first score appears, where it lands, and how to build it.
A dealer will tell you what you're approved for. That's a different question from what you can afford. Here's how to work it out from your income - including what each salary actually buys, and why the answer is usually a cheaper car than you were shown.
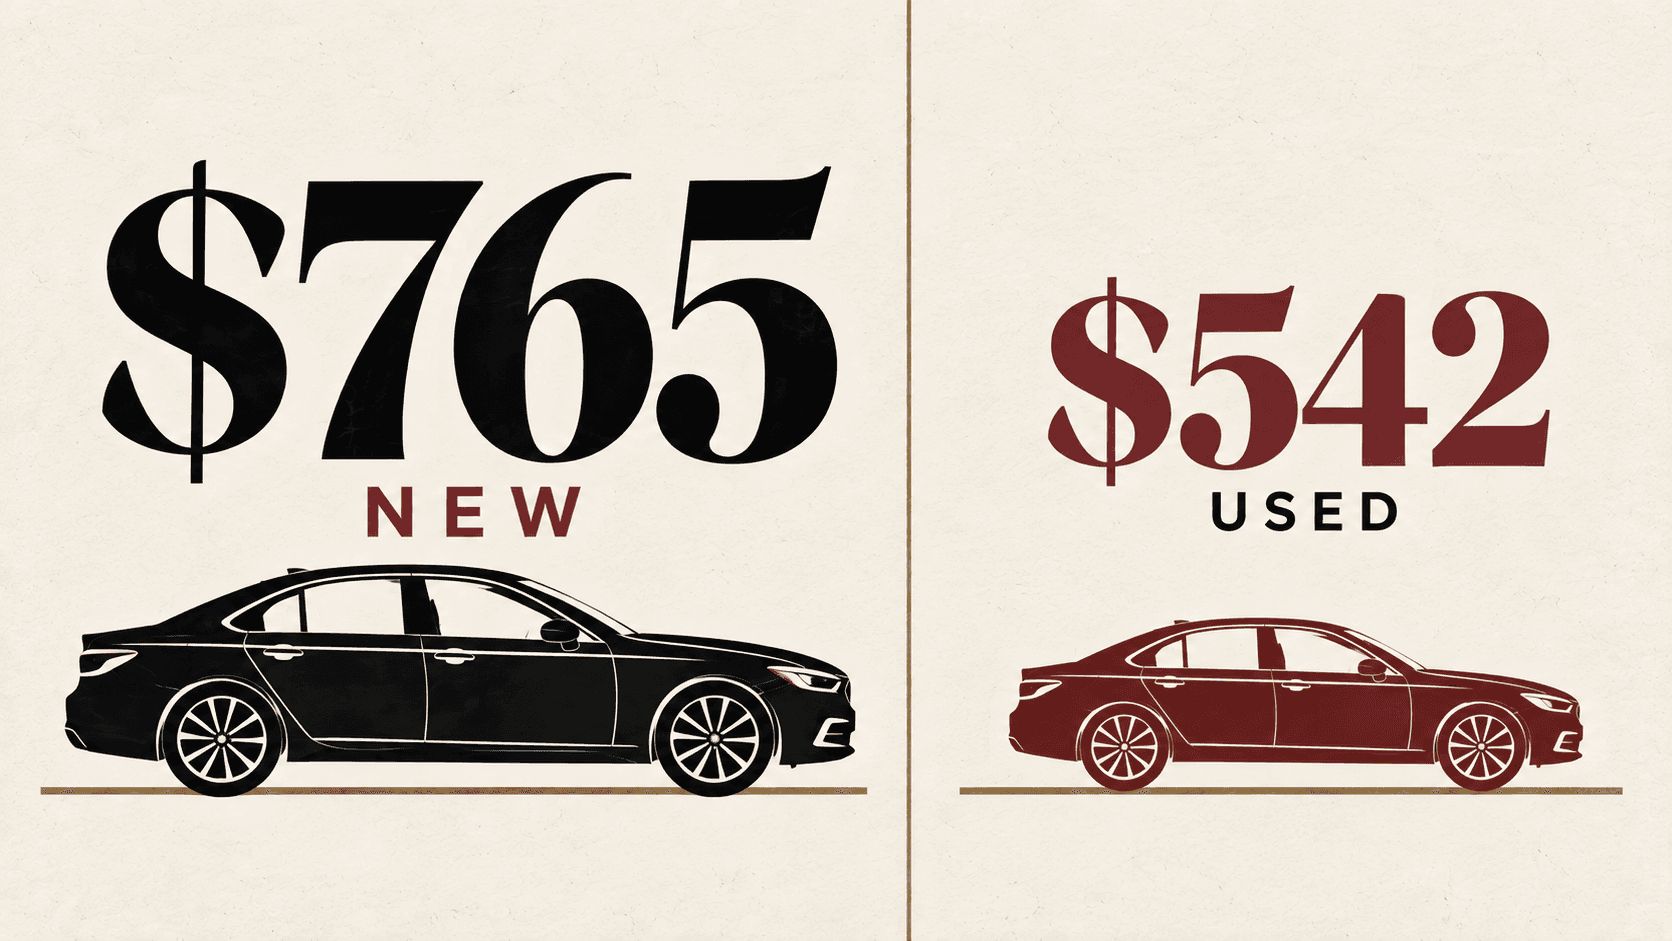
New car buyers are paying $765 a month on average, used car buyers $542. Here's what's driving those numbers, how your credit score changes them, and an honest answer to the question people really mean: is my own car payment too high?
Paying off a car loan early feels like the responsible move, and often it is. But not always. Here's the actual math on what early payoff saves you, the situations where it's clearly worth it, and the times your money genuinely does more good somewhere else.
A car loan lets you buy a vehicle now and pay it back monthly, with interest. Here's exactly how car loans work - the interest, the monthly payment, the term, and what a typical payment looks like - in plain English.
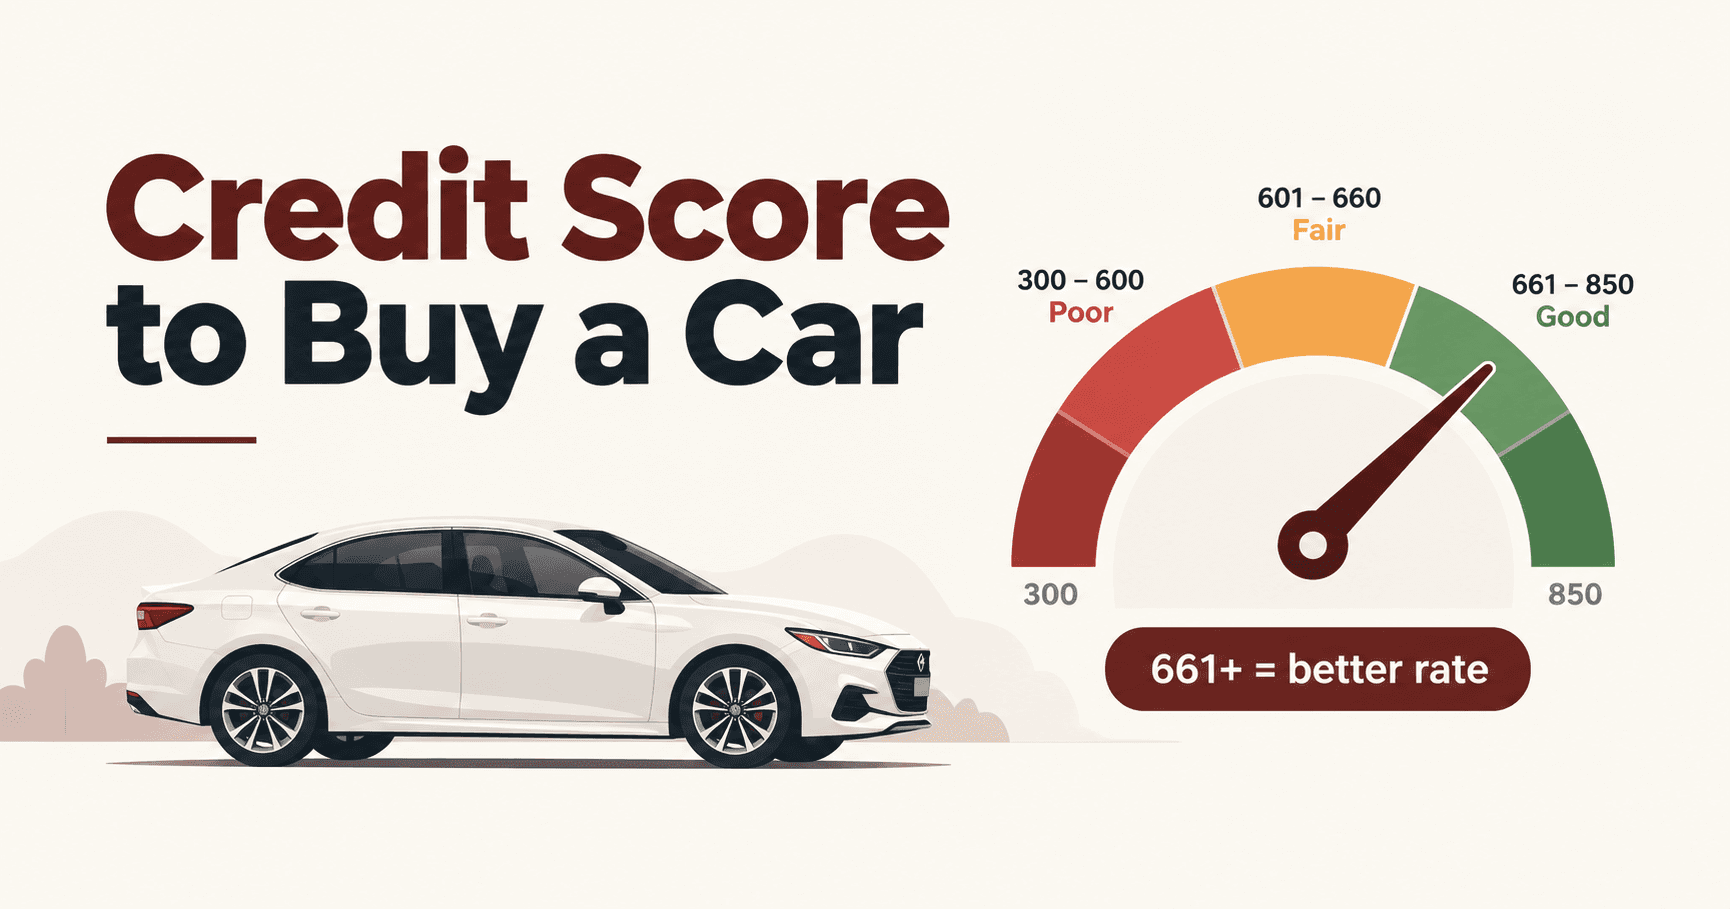
There's no single magic number, but most lenders want to see around 661+ for a good rate on a car loan. Here's the credit score you actually need to buy a car, the rate tiers lenders use, and how to raise your score fast before you apply.
A balloon payment car loan means lower monthly payments now and one large final payment later. Here's how it works, a clear example, the pros and cons, and your options when the balloon is due.
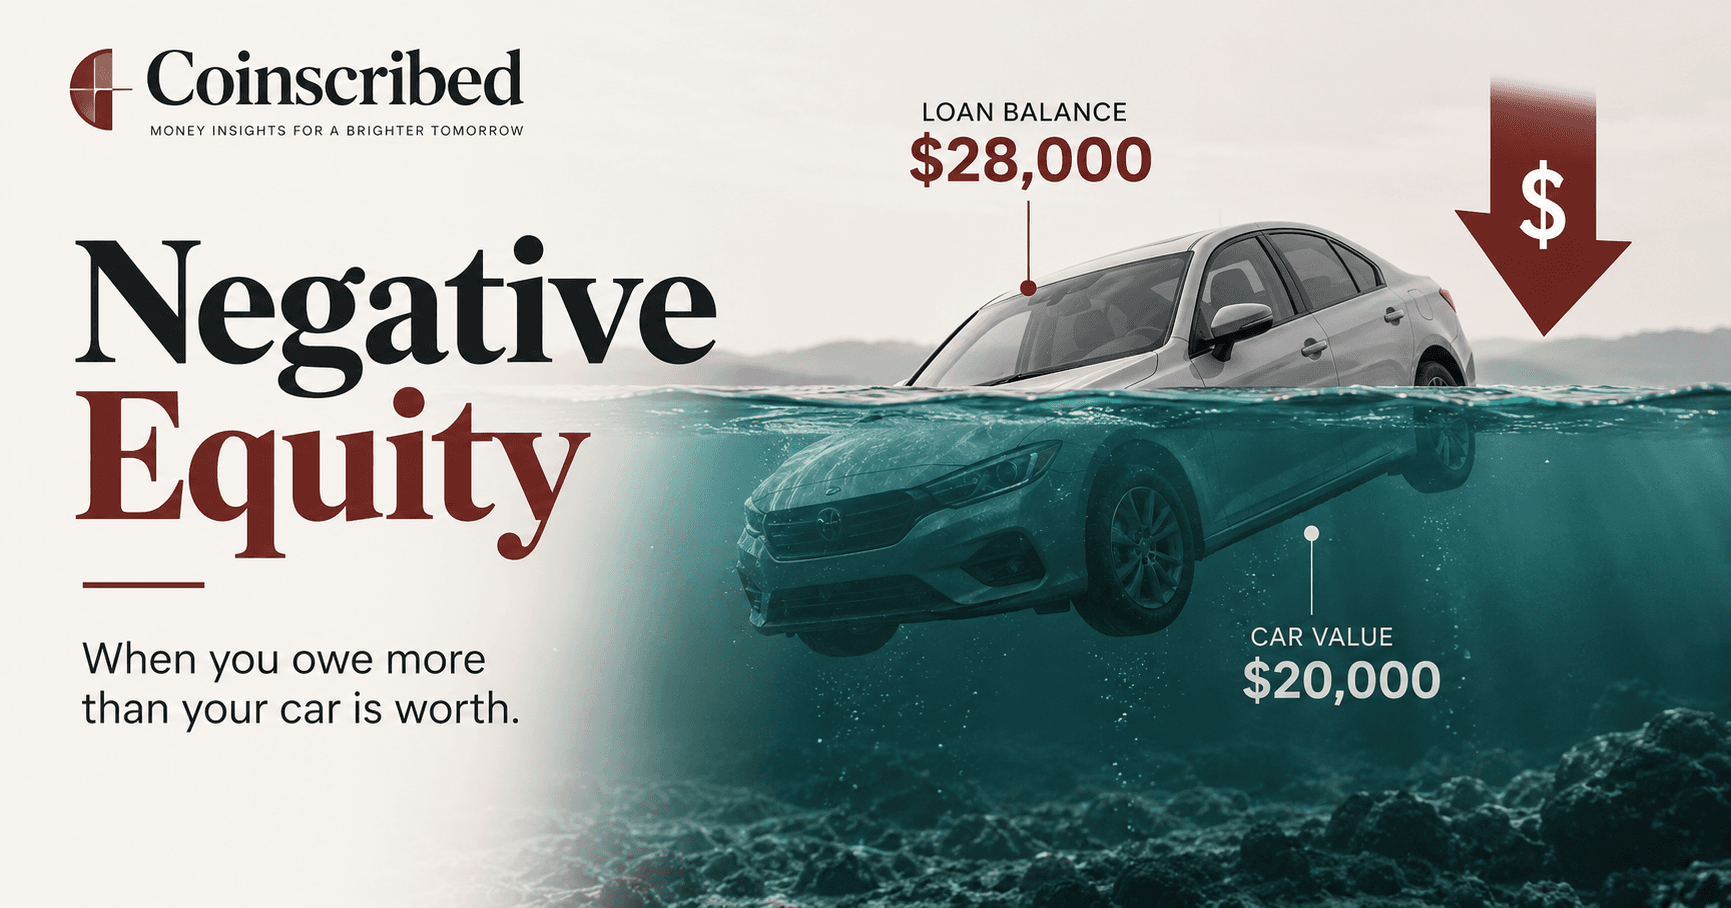
Owe more on your car than it's worth? That's negative equity - being "upside down" on your loan. Here's how to calculate it, why it happens, and how to get out.
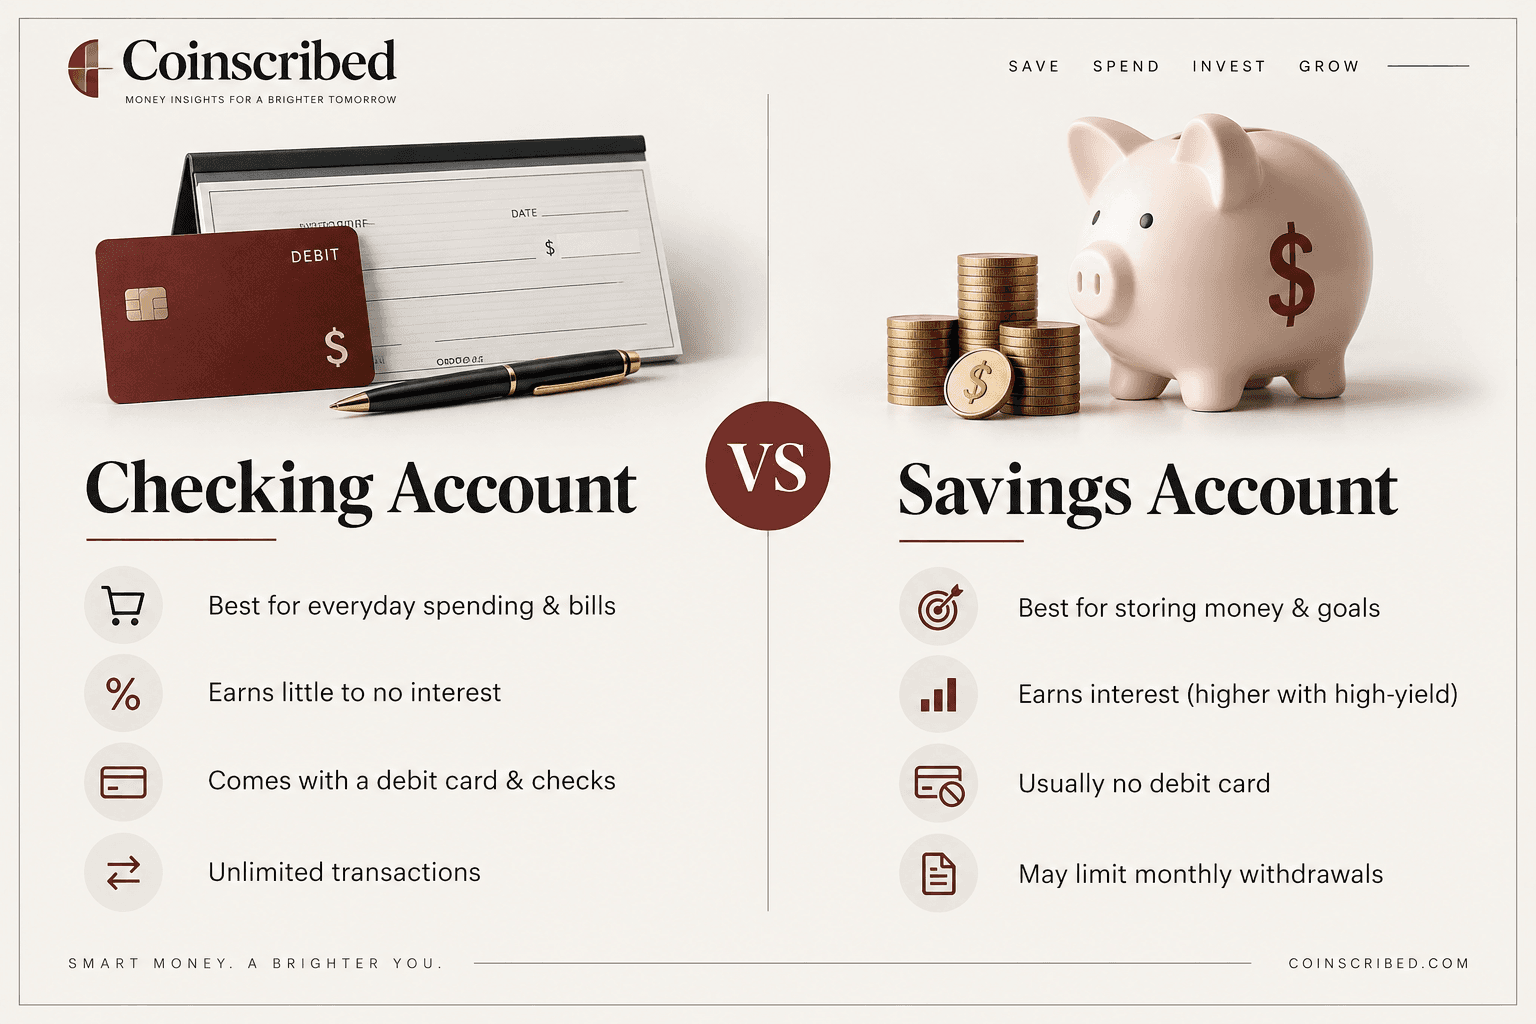
Not sure whether you need a checking account, a savings account, or both? Here's the simple difference between them, how each one works, and how to tell which type of account you already have.
PMI protects your lender, not you - so the sooner you drop it, the more you save. Here's how to get rid of PMI: the 6 ways to remove it, when it falls off automatically, how much equity you need, and the rules for FHA loans.