What Is a Good Credit Score? Ranges, Averages, and How to Get There
A good credit score is generally 670 or higher on the standard FICO scale of 300 to 850. Here's what the ranges actually mean, the average American score, the number you need for a house or car, and how to move up.
You pull up your credit score for the first time and see a 648. The app shows a colored gauge, a lender says it could be better, a friend says it's fine, and nobody tells you what the number actually means or what to do about it. That confusion is why this guide exists. A credit score looks like a mysterious three-digit verdict on your financial life, but it's really just a snapshot of how reliably you handle borrowed money. Below is exactly what counts as a good score, where you stand compared to other Americans, the numbers lenders want for a house or car, and the specific moves that raise it.
What Is a Good Credit Score?
A good credit score is generally 670 to 739 on the FICO scale, which runs from 300 to 850. Anything at or above 670 tells lenders you're a fairly low-risk borrower, which means easier approvals and better interest rates. Climb into the 740s and rates get competitive; the very best pricing usually starts around 780.FICO is the scoring model used in the vast majority of US lending decisions, so it's the scale that matters most. VantageScore (the other common model) uses the same 300-850 range with slightly different cutoffs, but if you aim for "670 and up," you're in good shape on either one.
Credit Score Ranges Explained
The credit score range runs from 300 to 850 on the FICO and VantageScore models that nearly every US lender uses. Lenders group that FICO score range into five bands, from poor to exceptional. Use this credit score range chart to see where any number falls and what it signals to a lender.
| Score range | Rating | What it means for you |
|---|---|---|
| 800–850 | Exceptional | Top-tier; you qualify for the best rates and terms available |
| 740–799 | Very Good | Above-average; you'll get very competitive rates |
| 670–739 | Good | The "good" zone; approvals are easy and rates are solid |
| 580–669 | Fair | Below average; you'll qualify but often at higher rates |
| 300–579 | Poor | Difficult to get approved; expect high rates or deposits |
The jump that matters most for your wallet is from Fair into Good. Crossing 670 is where borrowing gets noticeably cheaper - lower rates on cards, cars, and mortgages - so if you're sitting in the 640s or 650s, that's the milestone to chase first.
Related: How much of your credit limit you should actually use
What Is the Average Credit Score in America?
The average FICO score in the US is about 713 according to Experian's most recent consumer data, with FICO's own 2026 reading a point or two higher at around 714. Either way it sits comfortably in the "good" range and the small recent dip, the first in over a decade, is largely down to the return of student loan payments and general affordability pressure.
What Credit Score Do You Need to Buy a House?
For a conventional mortgage, most lenders want a score of at least 620, though you'll get better rates meaningfully at 700 and above. Government-backed FHA loans can go lower - sometimes down to 580 (or even 500 with a larger down payment) - which is why they're popular with first-time buyers still building credit. Here's the part people underestimate: on a mortgage, even a small rate difference tied to your score can cost or save you tens of thousands of dollars over the life of the loan. Raising your score from "fair" to "good" before you apply is one of the highest-value financial moves you can make. Once you're shopping, our Mortgage Calculator lets you see how different rates change your monthly payment.
What Credit Score Do You Need to Buy a Car?
There's no hard minimum for an auto loan - people finance cars across the whole score range - but the rate you're offered swings dramatically with your number. A borrower in the "exceptional" range might get a rate several percentage points lower than someone in "fair," which on a typical car loan means a real difference in the monthly payment and total interest.If your score is on the lower end and the purchase can wait a few months, spending that time raising your score often saves more than any dealer discount. If it can't wait, a larger down payment and a co-signer can help offset a lower score.
What Affects Your Credit Score the Most?
Your FICO score is built from five factors, and they're not weighted equally. Knowing the order tells you where to focus:
| Factor | Weight | What it tracks |
|---|---|---|
| Payment history | 35% | Whether you pay bills on time |
| Amounts owed (utilization) | 30% | How much of your available credit you're using |
| Length of credit history | 15% | How long you've had accounts open |
| Credit mix | 10% | The variety of credit types you manage |
| New credit | 10% | Recent applications and new accounts |
The two big ones, payment history and utilization, make up 65% of your score together. That's good news, because they're also the two you can change fastest: pay every bill on time, and keep your card balances well below their limits.
How to Improve Your Credit Score
You don't need tricks or paid "repair" services. The score responds to a handful of consistent habits:
- Pay every bill on time, every time. This is 35% of your score and the single most important thing. Set up autopay for at least the minimums so a late payment never sneaks through.
- Keep your credit utilization under 30%. Using less than 30% of your total credit limit helps; under 10% is even better. Paying your card down before the statement closes can lower the utilization that gets reported.
- Don't close your oldest cards. Length of history helps your score, so keep old accounts open (and used occasionally) even if you've moved on to better cards.
- Apply for new credit sparingly. Each application can cause a small, temporary dip, so don't open several accounts at once.
- Check your reports for errors. You're entitled to free reports from the three bureaus at AnnualCreditReport.com - disputing a genuine error can bump your score quickly.
Most of these work in the background once you set them up. My jump from the 640s to the 720s took about a year, and honestly, the hardest part was just paying attention for the first month.
Does Checking Your Own Credit Score Hurt It?
No - and this myth stops far too many people from tracking their progress. Checking your own score is a soft inquiry and never affects it. Only a hard inquiry, which happens when a lender pulls your credit for an application, can cause a small temporary dip. So check your score as often as you like; you can't hurt it by looking.
Good Credit Is a Tool, Not a Trophy
A good credit score isn't about bragging rights - it's about how much you pay to borrow for the big things in life. The difference between a 640 and a 760 can be tens of thousands of dollars across a mortgage, a car, and credit cards over the years. That's the real reason to care. And the two habits that move it most - paying on time and keeping balances low - are the same ones that keep the rest of your finances healthy. If you're carrying expensive credit card debt while trying to build your score, tackling that debt does double duty; here's how the debt snowball and avalanche methods can help you pay it down faster. Good credit and good money habits are the same project.
What Does a Specific Credit Score Mean?
People rarely look up a range - they look up the exact number they just saw on an app. Here's where the common ones land:
| Score | Band | What it means in practice |
|---|---|---|
| 655 | Fair | Just 15 points below "good." You'll be approved for most things, but not at the best rates - and this is the cheapest gap on the whole scale to close |
| 700 | Good | Comfortably past the 670 threshold and near the national average. Mainstream approvals, solid rates |
| 750 | Very good | Above average; competitive rates on most products |
| 780 | Very good | Effectively the ceiling for pricing - most lenders' best tier starts at or below here |
| 804 | Exceptional | Top quarter of consumers. No meaningful rate advantage over 780 |
| 820 | Exceptional | Same tier, same pricing. A strong file, not a different category of borrower |
| 844 | Exceptional | Six points from a perfect 850, which only 1.71% of people reach |
The pattern is worth internalising: the scale is not linear in value. Moving from 655 to 700 changes what you pay to borrow. Moving from 800 to 844 changes almost nothing. If your score is in the 600s, that's where the real money is.
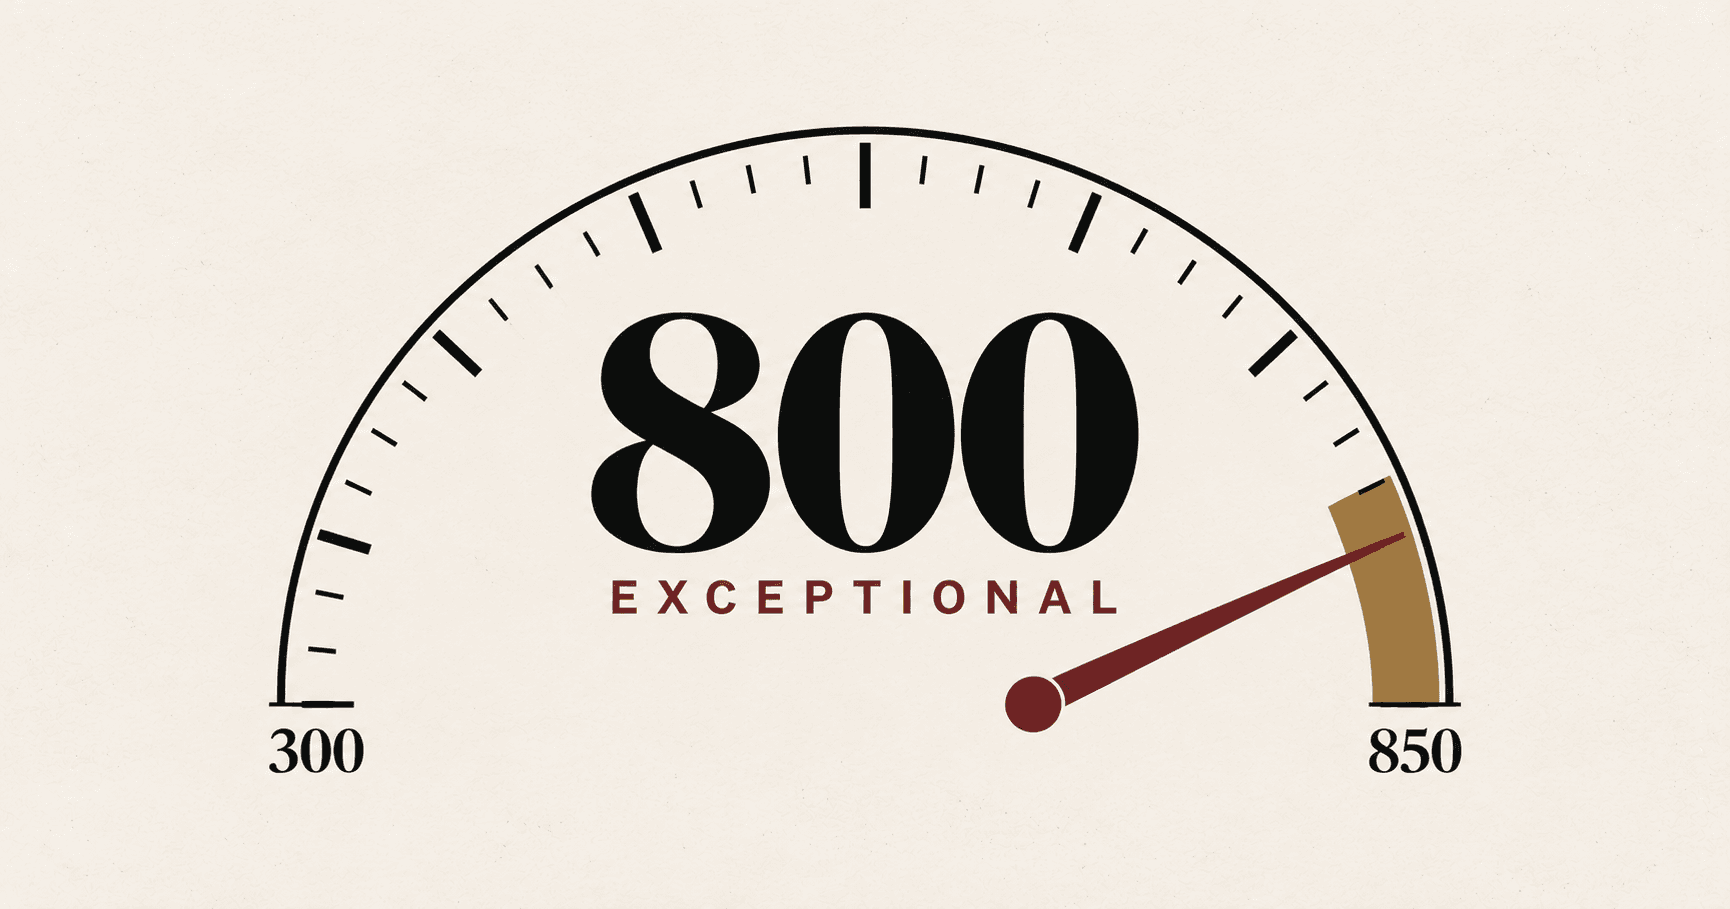
Is an 800 Credit Score Good? (And How Rare Is It?)
Yes - 800 sits in the "exceptional" band and is about as strong as a score needs to be. But it's less rare than people assume. According to Experian data from June 2026, roughly 23% of US consumers have a FICO Score of 800 or higher - about one in four.
A genuinely perfect score is another matter: only 1.71% of consumers reach 850, up slightly from 1.67% a year earlier.
Here's what nobody tells you before you start chasing points: the ones above roughly 780 buy you almost nothing. Most lenders reserve their best pricing for the upper 700s, around 780 and up, so the practical difference between a 780 and an 830 is close to zero. An 820 isn't a rarer key to cheaper credit - it's the same key with nicer engraving.
Which is why the valuable jumps aren't at the top at all. They're crossing 670 into "good," and then reaching the 740s, where competitive rates genuinely begin.
Average Credit Score by Age
Scores climb with age, and the spread between generations is wide. Approximate averages from Experian's data:
| Generation | Approximate average FICO Score |
|---|---|
| Gen Z | About 680 |
| Millennials | About 690 |
| Gen X | About 710 |
| Baby Boomers | About 745 |
| Silent Generation | About 760 |
Nearly 70 points separate the youngest adults from the oldest, and hardly any of it is about discipline. Length of credit history is 15% of a FICO Score, and it is the one factor nobody can speed up. A 26-year-old paying every bill on time cannot manufacture twenty years of history.
So if you're in your twenties and sitting in the 600s, you aren't behind your peers - you're where the maths puts you. Compare yourself against your own age band rather than the national average, keep the accounts open, keep the payments on time, and the gap closes by itself.
Related: Does paying off a credit card increase your credit score?
Is Your Specific Credit Score Good? A Score-by-Score Guide
Short answer: On the 300 to 850 FICO scale, 670 and up is "good," 740 and up is "very good," and 800 and up is "exceptional." Anything in the 580 to 669 band is "fair," and below 580 is "poor." So a 700 is good, a 640 is fair, and a 760 is very good. Where you land matters less than which side of 670 you are on, because that is the line most mainstream rates are built around.
People rarely search "what is a good credit score." They search their own number: is a 640 good, is a 672 good, is a 705 good. The honest answer is that a single point almost never changes a lending decision.
What changes it is the band your score sits in, because lenders price in tiers, not point by point. Here is where the common scores fall and what each one realistically gets you.
| Score | Band | What it realistically means | Avg new-car APR |
|---|---|---|---|
| 520 | Poor | Below 580. Approvals are hard; expect deposits, co-signers, or deep-subprime rates. The fastest fix is on-time payments and lowering card balances | About 16.1% |
| 585 | Fair (low) | Just into the fair band. You can be approved, but pricing is steep. A few months of clean payments can move you toward 600+ | About 13.5% |
| 620 | Fair | A common mortgage-floor number. Many conventional and FHA programs start here, though the rate is well above prime | About 9.7% |
| 640 | Fair | Approvable for most products, but you are paying the "fair" premium. You are about 30 points from the "good" line | About 9.7% |
| 662 | Fair (top edge) | Only 8 points under "good." This is the cheapest gap on the scale to close; small utilization and payment wins can push you over 670 | About 6.2% |
| 668 | Fair (top edge) | Two points under the 670 "good" line. Because lenders price in tiers, a 668 and a 672 usually cost the same — but some automated cutoffs sit exactly at 670, so this is the most frustrating place on the scale to sit | About 6.2% |
| 678 | Good | Over the line. Mainstream approvals open up and rates become solid rather than penalized | About 6.2% |
| 682 | Good | Clearly over the line. This is the classic "just became good" score: mainstream card and loan approvals open up, though not the best pricing tier yet | About 6.2% |
| 692 | Good | Solidly good and closing on the US average of 713. Most everyday credit is available at fair rates | About 6.2% |
| 705 | Good | Comfortably good and near the US average of 713. You will qualify for most everyday credit at fair rates | About 6.2% |
| 727 | Good (top edge) | Near the top of "good." A few more points moves you into the "very good" tier, where the best everyday pricing starts | About 6.2% |
| 746 | Very good | Just past the 740 line, so you are in the "very good" band. The next meaningful pricing step is around 780, not 800 | About 6.2% |
| 753 | Very good | Above average. You get very competitive rates on most products and easy approvals | About 6.2% |
| 765 | Very good | Strong file. The gap to the best-priced tier is small and buys a cushion more than a lower rate | About 6.2% |
Two things to read from that table. First, the US average FICO is 713, so a score in the low 700s is squarely normal, not exceptional. Second, the dollar difference between "fair" and "good" is large, while the difference between "very good" and "exceptional" is small.
Experian's average new-car rates for Q2 2026 run about 13.5% at a 585, about 9.7% in the low 600s, about 6.2% once you clear 661, and about 4.4% once you pass 780. The expensive gap is the one below 670, which is exactly why closing it is the highest-value move for most people.
Is a 640 credit score good?
No, 640 is "fair," not good. You will be approved for most loans and cards, but at rates above what someone over 670 pays. The upside is that 640 is close to the line. Lowering your credit-card utilization and letting on-time payments age are often enough to reach the "good" band within a few months.
Is a 672 credit score good?
Yes, barely. A 672 just clears the 670 "good" threshold, so mainstream approvals and solid rates are available. It is at the lower end of good, so you will not see the best everyday pricing yet, but you are out of the "fair" penalty zone.
Is a 705 credit score good?
Yes. A 705 is comfortably in the "good" band and sits just under the US average of 713. You will qualify for most credit products at competitive, if not best-in-class, rates. Pushing past 740 is what opens the "very good" pricing tier.
Is a 753 credit score good?
Yes, a 753 is "very good." It is above the national average and earns very competitive rates on cards, auto loans, and mortgages. The remaining gap to "exceptional" (800+) buys a small cushion rather than a meaningfully lower rate, because most lenders' best pricing tier starts around 780.
What about a score below 580?
Scores under 580 are "poor." Approvals are harder and often come with deposits, co-signers, or the highest rate tiers. This is not permanent. Because payment history (35%) and amounts owed (30%) drive two-thirds of a FICO score, the two moves that help fastest are never missing a due date and getting card balances down. For a step-by-step plan, see our guide on where credit scores start and how to build from scratch.
Is a 668 credit score good?
Not quite. A 668 is the top of the "fair" band, two points under the 670 line where "good" begins. In practice almost nothing changes between a 668 and a 672 — lenders price in tiers, not single points, and both land in the same auto-loan pricing tier at roughly 6.2% on a new car. What does change is the handful of automated approval rules set exactly at 670. If you are at 668, the cheapest way over the line is lowering your card balances before the statement closes, because utilization updates faster than anything else on your file.
Is a 682 credit score good?
Yes. A 682 is in the "good" band (670–739), so mainstream credit cards, auto loans and mortgages are available at reasonable rates. It is still in the lower half of good, so you are not seeing the best everyday pricing — that tends to start around 740 and again near 780. A 681 is the same answer; one point does not move a lending decision.
Is a 692 credit score good?
Yes, and it is close to typical. A 692 is comfortably "good" and sits just under the US average FICO Score of 713. You will qualify for most everyday credit without penalty pricing. The next real step up is 740, where the "very good" tier begins.
Is a 746 credit score good?
Yes - a 746 is "very good," not just good. It clears the 740 threshold, so you are past the point where rates stop being the main obstacle. Worth knowing: the best-priced tier at most lenders starts nearer 780 than 800, so the remaining gap is smaller than people assume. Our guide to what an 800 credit score actually gets you covers that last stretch.
Our take: stop chasing a specific number. The only line that changes your pricing in a big way is 670, and the next one is roughly 780. If you are under 670, closing that gap is the best return on effort you can get in personal finance. If you are already over 740, you have essentially won the rate game; more points mostly buy bragging rights. For the mechanics of getting to the top tier, read what an 800 credit score actually gets you, and use our credit card payoff calculator to see how fast lowering a balance can move your utilization.
Frequently Asked Questions
- What is a good credit score?
- A good credit score is generally 670 to 739 on the FICO scale, which ranges from 300 to 850. Scores of 740 to 799 are considered very good, and 800 and above are exceptional. At 670 or higher, most lenders view you as a low-risk borrower and offer easier approvals and better rates.
- What is the average credit score in the US?
- The average FICO credit score in the US was about 713 in 2025, which falls within the "good" range. That number rose steadily for over a decade before a small recent decline. A score in the low 700s puts you right around the national average.
- What credit score do you need to buy a house?
- Most conventional mortgages require a minimum score of about 620, though you'll get much better rates at 700 or higher. FHA loans can go lower - often to 580, or 500 with a larger down payment - making them common for first-time buyers still building credit.
- What credit score do you need to buy a car?
- There's no strict minimum for an auto loan, but your score heavily affects the interest rate you're offered. Borrowers with scores in the "very good" or "exceptional" range get the lowest rates, while lower scores mean higher rates, so a higher score can meaningfully lower your monthly payment.
- What is the biggest killer of credit scores?
- Missing payments are the biggest damage to a credit score, since payment history makes up 35% of your FICO score. High credit utilization - using a large share of your available credit - is the second biggest factor at 30%. Fixing these two has the fastest impact.
- Does checking your own credit score lower it?
- No. Checking your own credit score is a soft inquiry and never affects your score, so you can check it as often as you want. Only hard inquiries, which occur when a lender reviews your credit for an application, can cause a small temporary dip.
- Can I get a $50,000 loan with a 700 credit score?
- A 700 credit score is in the "good" range and generally strong enough to qualify for a $50,000 loan, though approval also depends on your income, existing debts, and the lender. A higher score would typically earn you a lower interest rate on that loan.
- How can I raise my credit score fast?
- The fastest levers are paying down credit card balances to lower your utilization below 30%, making all payments on time, and disputing any errors on your credit reports. Avoid opening several new accounts at once, and keep older accounts open to protect your length of credit history.
- What is the credit score range?
- The most widely used credit score range is 300 to 850, used by both FICO and VantageScore. Within that range, scores are commonly grouped as poor (300–579), fair (580–669), good (670–739), very good (740–799) and exceptional (800–850). Most lenders treat 670 and above as good credit, which is where you start qualifying for meaningfully better interest rates.
- Is an 800 credit score good?
- Yes - 800 sits in FICO's "exceptional" band (800–850) and is about as strong as a score needs to be. It's also not especially rare: roughly 23% of US consumers score 800 or higher as of June 2026. Worth knowing that most lenders' best pricing begins around 780, so an 800 rarely earns you a better rate than a 780.
- How rare is an 820 credit score?
- Not as rare as people expect. About one in four US consumers score 800 or above, and an 820 sits inside that same group. A genuinely perfect 850 is rare - only 1.71% of consumers reach it. For borrowing purposes, an 820 and a 780 are treated almost identically.
- What is a 655 credit score?
- 655 falls in the "fair" band (580–669), just 15 points below the 670 "good" threshold. You'll qualify for most credit at 655, but at higher rates than a little further up the scale. It's the most worthwhile stretch on the entire range to close, and lowering your credit utilization is usually the fastest way to do it.
- What is the average credit score by age?
- Approximate Experian averages run from about 680 for Gen Z to roughly 690 for millennials, 710 for Gen X, 745 for baby boomers and 760 for the silent generation. The gap is mostly length of credit history, which is 15% of a FICO Score and cannot be sped up - so compare your score with your own age group rather than the national average.
- What is the highest credit score possible?
- 850 on both FICO and VantageScore. Scores above that - a 900, for instance - don't exist on the models US lenders actually use, despite how often that number gets mentioned. Only 1.71% of consumers reach 850, and there's no practical benefit over the high 700s.
- Is a 640 a good credit score?
- No. A 640 falls in the "fair" band (580 to 669), one tier below "good." You can still get approved for most loans and credit cards, but at higher rates than someone over 670. Because 640 is close to the line, lowering card balances and paying on time can move you into "good" fairly quickly.
- Is a 700 credit score good?
- Yes. A 700 is in the "good" band (670 to 739) and sits just below the US average of 713. You will qualify for most mainstream credit at solid rates. Reaching 740 moves you into "very good," where the best everyday pricing begins.
- Is a 672 credit score good?
- Yes, just barely. A 672 clears the 670 threshold for "good," so you are out of the "fair" penalty zone and can get mainstream approvals at reasonable rates. It is at the low end of good, so the very best pricing still takes a few more points.
- Is a 753 credit score good?
- Yes. A 753 is "very good" (740 to 799), above the national average, and earns very competitive rates on cards, auto loans, and mortgages. The gap to "exceptional" (800+) buys a small cushion rather than a meaningfully lower rate.
- What does a 620 credit score get you?
- A 620 is "fair." It is a common minimum for conventional and FHA mortgages and for most auto loans, but the rate sits well above what a borrower over 670 pays. On the Experian Q2 2026 averages, a score in the low 600s pays roughly 9.7% on a new-car loan versus about 6.2% once you clear 661.
- Is a credit score below 580 bad?
- It is "poor," the lowest band, so approvals are harder and often come with deposits, co-signers, or the highest rate tiers. It is fixable: payment history and amounts owed drive about two-thirds of a FICO score, so paying on time and lowering card balances are the fastest ways up.
- Is a 668 credit score good or bad?
- Neither, strictly - 668 is the top of the "fair" range, two points below the 670 start of "good." It is approvable for most products at mid-tier rates. Because scoring and pricing work in bands, a 668 and a 672 usually cost the same, but some lenders set automatic cutoffs at exactly 670.
- Is 682 a good credit score to buy a car?
- Yes. A 682 falls in Experian's prime auto tier (661–780), which averaged about 6.2% on a new car and 8.8% on a used car in Q2 2026. You will be approved by mainstream lenders, though buyers above 780 average about 4.4% on a new car.
- What is the difference between a 668 and a 682 credit score?
- One is "fair" and one is "good," but the practical difference is small: both sit in the same auto-loan pricing tier. The 670 line matters because it is where many lenders' automated rules and marketing tiers begin, not because 14 points change your risk.
Sources
- Experian data from June 2026 (experian.com)
- Experian: What is a good credit score? (experian.com)
- Experian: What is the average credit score in the US? (experian.com)
- myFICO: What’s in your credit score (myfico.com)
- CFPB: How do I get a free copy of my credit reports? (consumerfinance.gov)
Get new money guides and tools in your inbox
New guides, calculators and data studies when they publish. No spam, unsubscribe anytime.